VA Loan Timeline: How Long Does It Take to Get Approved?
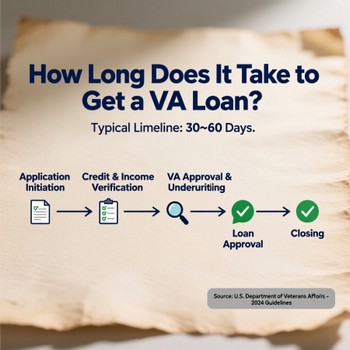 Understanding the VA loan timeline is essential for military families planning a home purchase. Most borrowers can expect the VA loan approval process to take 30 to 45 days from application to closing, though some cases may extend to 50 days depending on market conditions and your specific financial profile. Unlike the uncertainty of conventional lending, the VA loan timeline follows a predictable sequence: prequalification, Certificate of Eligibility verification, underwriting, appraisal, and final closing. By knowing each stage of the VA loan timeline, you can set realistic expectations and prepare your documentation in advance.
Calculate your VA funding fee to understand the full cost of your loan.
VA Loan Timeline Overview: Five Key Stages
The VA loan timeline breaks down into five critical stages, each with its own processing window. Understanding these phases helps you stay on track and avoid delays. Here's what to expect:
- Prequalification: 1–3 days
- Certificate of Eligibility & Initial Review: Immediate to 3-5 business days
- Underwriting & Appraisal: 1–2 weeks
- Final Underwriting Review: 1 week (often concurrent with appraisal)
- Loan Closing: 1–2 weeks after final approval
Stage 1: Prequalification and Application (1–3 Days)
The first step in your VA loan timeline is prequalification, which typically takes just 1 to 3 days if you have all required documents ready. During prequalification, your lender reviews your credit score, income, employment history, and debt-to-income ratio to determine how much you can borrow. Having your financial documents organized before you apply - including pay stubs, tax returns, and bank statements - accelerates this phase significantly.
Getting prequalified early in your VA loan timeline shows sellers you're a serious buyer with financing lined up. Many real estate agents prioritize working with prequalified borrowers because they understand the competitive advantage in active markets.
Stage 2: Certificate of Eligibility and Initial Processing (Immediate to 5 Days)
Your Certificate of Eligibility for a VA loan is the foundation of your application. This document proves you qualify for VA loan benefits based on your military service. The good news: most certificates are approved within a few business days, and many lenders can pull this information directly from VA systems.
You can obtain your certificate online through the VA's eBenefits portal, by mail, or through your lender. If you've used your VA loan before, your certificate will show your remaining eligibility balance. This early verification helps keep your overall VA loan timeline on schedule.
Stage 3: Initial Underwriting Review (3–5 Business Days)
Once your Certificate of Eligibility is verified, the lender begins the initial underwriting review. During this phase (typically 3 to 5 business days), an underwriter examines your application to verify income, employment, credit history, and financial assets. This stage is more cursory than full underwriting but establishes whether your application meets basic VA loan requirements.
Borrowers with clean credit reports and stable employment history move through this phase quickly. If your situation includes unusual income sources or recent employment changes, the underwriter may flag your file for deeper review, potentially extending this stage of the VA loan timeline.
Stage 4: VA Appraisal and Full Underwriting (10–14 Days)
The VA appraisal is the most time-intensive component of the VA loan timeline. Every VA home loan requires a VA appraisal to determine the property's fair market value and ensure it meets minimum property requirements. This stage typically takes 10–14 business days from start to finish.
How Long Does Scheduling Take?
Scheduling the VA appraisal depends on local market conditions. In hot housing markets with high buyer demand, appraisers may have 1–2 week wait times. In rural areas or slower markets, scheduling can be faster but may require traveling appraiser availability. This is often the longest single component of your overall VA loan timeline.
How Long Does the Appraisal Inspection Take?
The actual VA appraisal inspection takes just a few hours. The appraiser inspects the property inside and out, checks for structural defects, verifies utilities, and assesses overall condition. The appraiser then has up to 10 business days to complete and submit their report - most finish within this window.
Concurrent Underwriting During Appraisal
Full underwriting typically occurs while the appraisal is in progress, which helps compress your overall VA loan timeline. The underwriter reviews your complete financial picture in detail: employment verification, asset documentation, tax returns, and debt obligations. This step usually takes 1–2 weeks and is the most thorough review of your application.
Stage 5: Final Approval and Loan Closing (1–2 Weeks)
Once the appraisal is complete and full underwriting is finished, your loan moves to final approval. At this stage, the underwriter has all information needed to make a clear-to-close decision. If everything is in order, final approval typically takes just a few days.
After receiving clear-to-close status, you'll enter the loan closing phase, which takes 1–2 weeks. During this time, your lender prepares all final closing documents, and you'll receive your Closing Disclosure at least three days before closing (required by federal law). Review this document carefully to confirm your final interest rate, loan terms, and closing costs.
The actual closing appointment takes 1–2 hours, during which you'll sign all loan documents and transfer funds. After closing, your loan moves to loan servicing for ongoing payment processing and account management.
Factors That Speed Up or Slow Down the VA Loan Timeline
Factors That Accelerate Your VA Loan Timeline
- Having all required documents ready before applying
- Choosing an experienced VA-approved lender with established appraiser relationships
- Maintaining stable employment and clean credit history
- Responding quickly to any lender requests for additional information
- Obtaining your Certificate of Eligibility early in the home-buying process
- Selecting a property in good condition that meets minimum requirements
Factors That Extend the VA Loan Timeline
- Peak home-buying seasons (spring/summer) when lender workload is high
- Employment or income verification issues requiring additional documentation
- Complex financial situations (self-employment, recent job change, multiple income sources)
- Property defects requiring repairs or additional inspections
- Appraiser shortages in rural or remote areas
- Incomplete initial documentation requiring multiple document requests
- Market delays in local real estate transactions
VA Loan Timeline vs. Other Loan Types
How does the VA loan timeline compare to conventional and FHA loans? The VA process typically takes 30–45 days, matching conventional loans. However, VA appraisals (10–14 days) take slightly longer than conventional appraisals (7–10 days) because VA appraisers are more thorough in checking minimum property requirements. VA loans vs. conventional loans have similar overall timelines, but VA loans offer better benefits like no down payment and no PMI - making the slightly longer appraisal worth the wait for most military families.
How to Speed Up Your VA Loan Approval Timeline
1. Prepare All Documents Before Applying
Your lender needs pay stubs, W-2s, tax returns (usually 2 years), bank statements, employment verification, and military discharge papers. Having these organized and ready prevents delays and keeps your VA loan timeline on track. Use a checklist from your lender to ensure nothing is missing.
2. Get Your Certificate of Eligibility Early
Don't wait until you've found a home to obtain your Certificate of Eligibility. Apply through the VA's eBenefits portal or ask your lender to pull it from VA systems. This single document can be retrieved in days, removing a bottleneck from your overall VA loan timeline.
3. Choose an Experienced VA Mortgage Lender
Not all lenders are equally efficient with VA loans. Choose a VA-approved lender with proven experience. These lenders have established relationships with VA appraisers, understand VA requirements inside and out, and avoid common mistakes that delay processing. They can often expedite scheduling and reduce underwriting delays.
4. Maintain Clear Communication
Stay in constant contact with your loan officer and underwriter. Respond to document requests within 24 hours when possible. If you're asked for clarification, provide it immediately. Quick responses keep your application moving forward without unnecessary holds.
5. Work with a VA-Experienced Real Estate Agent
Your real estate agent influences your VA loan timeline. Agents experienced with VA loans understand the appraisal process, know how to write offers with realistic contingency timelines, and won't pressure you into unrealistic closing dates. This partnership helps keep everything aligned with your actual VA loan timeline.
Why Understanding the VA Loan Timeline Matters
Knowing your VA loan timeline helps you plan your home purchase strategically. You can coordinate your house hunting with your prequalification timeline, set realistic offer deadlines with sellers, and avoid the stress of unexpected delays. When both you and your real estate agent understand how long each step takes, negotiations flow more smoothly and closing surprises are minimized.
The 30–45 day VA loan timeline is competitive with conventional loans, and the benefits - zero down payment, no PMI, favorable interest rates, and the ability to refinance later - make the slightly longer appraisal phase worth it for veterans and active-duty service members.
Common Questions About the VA Loan Timeline
Can the VA loan timeline be shortened below 30 days?
It's rare but possible. In perfect conditions - complete documentation, excellent credit, experienced lender, available appraiser, property in good condition - some borrowers have closed in 25–28 days. However, 30–45 days is the realistic expectation, and most lenders won't guarantee faster timelines.
What happens if the VA appraisal comes back low?
If the VA appraisal comes back lower than the purchase price, you have options: renegotiate the purchase price, make up the difference with cash, or walk away. This won't necessarily extend your VA loan timeline - the decision is usually made within a few days. Be sure to discuss this scenario with your lender upfront.
Can I close before 45 days if the market is slow?
Market speed doesn't determine your VA loan timeline - the appraisal and underwriting do. Even in slow markets, the appraisal still takes 10–14 days. However, a slower market might mean appraisers are more available, potentially speeding up scheduling slightly.
Does my lender's location affect the VA loan timeline?
Most modern VA lenders process loans remotely, so geographic location matters less than lender experience. What matters more is the lender's relationships with local appraisers and their familiarity with your state's real estate requirements. Some states have additional closing requirements that add 1–2 days.
Plan Ahead for Your VA Loan Timeline
Start your VA loan timeline early - even before house hunting. Get prequalified, obtain your Certificate of Eligibility, and choose a VA-experienced lender and real estate agent. When you find a property, you'll already be positioned to move quickly. This preparation ensures your 30–45 day timeline stays on track and you can close with confidence.
Ready to understand the full cost? Try our VA funding fee calculator to see exactly what you'll pay.
Connect With Us
Please share – it really helps