How Many Times Can You Use a VA Home Loan? Unlimited
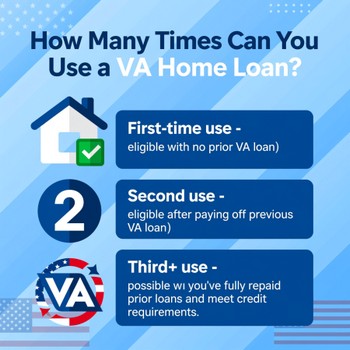 A VA home loan is one of the most powerful homeownership benefits available to eligible veterans and active-duty service members. One of the greatest advantages is that you can use your VA home loan benefit unlimited times throughout your life. Unlike conventional mortgages or many other loan programs with single-use limitations, the VA loan program recognizes that veterans' housing needs evolve with military relocation, family changes, and life transitions. Understanding how entitlement works and how to restore it are the keys to unlocking multiple VA loans over your lifetime.
How Many Times Can You Use a VA Home Loan?
The answer to this frequently asked question is straightforward and encouraging: there is no limit to how many times you can use a VA home loan. Veterans can apply for VA loans repeatedly throughout their lives, provided they meet the VA's eligibility requirements and have available entitlement. This unlimited access to VA financing sets the program apart from many other government-backed mortgage programs and represents exceptional value for the military community.
The primary factor that determines your ability to use a VA loan multiple times is your entitlement status. Each time you use your VA loan, a portion of your entitlement is utilized. However, once you satisfy certain conditions, your entitlement can be restored, allowing you to borrow again.
Understanding VA Loan Entitlement
To fully grasp how many times you can access this program, it's essential to understand VA loan entitlement. Entitlement is the dollar amount that the Department of Veterans Affairs (VA) guarantees to a lender when you borrow for a home purchase. This guarantee protects the lender if you default on the loan, making it easier for veterans to qualify and often secure better terms than conventional borrowers.
What Is VA Loan Entitlement?
VA loan entitlement represents the maximum dollar amount the VA will guarantee on a mortgage. Most eligible veterans receive basic entitlement, currently set at $36,000 (though this amount has increased over time). Veterans who have used their benefit and repaid the loan in full may also be eligible for additional or bonus entitlement, which allows them to borrow larger amounts without a down payment.
There are two main types of entitlement to be aware of:
- Basic entitlement: The standard guaranteed amount available to all eligible veterans, enabling them to access favorable VA loan financing.
- Additional or bonus entitlement: Extra guarantee available to veterans who have previously used their VA loan benefit and either repaid it or restored their entitlement, allowing higher borrowing capacity without requiring a down payment.
How Entitlement Affects Borrowing Capacity
Your available entitlement directly impacts how much you can borrow when you use your VA home loan. Lenders use entitlement to calculate your maximum loan amount based on local VA loan limits for your county. If you have full entitlement available, you generally qualify for the highest loan amount in your area without a down payment. If you've previously used your entitlement and haven't fully restored it, your remaining available entitlement will limit the amount you can borrow on your next VA loan.
This system ensures that you can leverage your VA benefit multiple times, but the amount available on each subsequent loan depends on how much entitlement remains.
Restoring Your VA Loan Entitlement
The pathway to using your VA home loan multiple times is through entitlement restoration. If you've already used your benefit and want to purchase another property, you can restore your full entitlement under specific circumstances.
Methods to Restore Your Full Entitlement
The most straightforward method to restore your VA loan entitlement is to sell the home and pay off the VA mortgage in full. Once you've satisfied the loan, your entitlement is automatically restored to its original amount. This restoration allows you to apply for a new VA loan with full entitlement, essentially resetting your benefits for the next property purchase.
Some veterans have the financial means to pay off the loan without selling, which also restores their entitlement. However, this is less common due to the large amount of capital required.
Additionally, if a previous owner assumes your VA loan, your entitlement may be released early, allowing you to use your benefit again before the original loan is fully paid.
Using a VA Loan Multiple Times
The flexibility of the VA loan program is one of its greatest strengths. Veterans can use this benefit multiple times to adapt to life changes such as military relocations, career transitions, or expanding family needs.
Scenario 1: Sequential VA Loans (One Home at a Time)
Many veterans use their VA loans sequentially. They purchase a home with full entitlement, live in it for several years, then sell it and move to another location. Once the first home is sold and the mortgage paid off, their entitlement is restored, and they can apply for a second VA loan with the same benefits as the first. This cycle can repeat unlimited times throughout their life.
Scenario 2: Using Your VA Loan While Paying Off Another
Some veterans need to purchase a second home before selling their first property. In this situation, you may be able to take out a second VA loan while still paying off the original mortgage, provided you have sufficient remaining entitlement. The VA will assess your debt-to-income ratio and your ability to manage both mortgages simultaneously. If you qualify, you can hold multiple VA loans at the same time.
However, managing two mortgages requires careful financial planning. The VA typically prefers that the second property be your primary residence, not an investment property. You'll also want to consider the long-term financial burden of carrying two mortgages.
Scenario 3: Restoring Entitlement Before Your Next Purchase
The strategic approach many veterans take is to sell their home and pay off the VA mortgage before applying for the next loan. This restores your full entitlement, potentially avoiding the VA funding fee on the subsequent loan and maximizing your borrowing power.
Applying for a New VA Loan After Previous Use
The application process for a second, third, or subsequent VA loan is similar to your first application. Here's what you need to know:
Step 1: Verify Your Entitlement Status
Before applying, obtain an updated Certificate of Eligibility (COE) from the VA that reflects your current entitlement. You can request a COE through VA.gov or work with your lender to verify your available entitlement.
Step 2: Get Pre-Approved by a Lender
Work with a VA-approved lender to understand how much you can borrow based on your remaining entitlement, income, and debt-to-income ratio. The lender will calculate your maximum loan amount using the local county loan limits and your available entitlement.
Step 3: Submit Your Application with Documentation
You'll provide similar documentation as before: proof of income, employment verification, credit authorization, and a completed application form. The underwriting process will review your financial situation to ensure you can handle the new loan.
Step 4: Close on Your New Home
Once approved, you proceed to underwriting and closing, just as with your first VA loan. If you've fully restored your entitlement by paying off a previous loan, you may qualify for a VA funding fee exemption or reduced fee on the subsequent loan.
Managing Multiple VA Loans Simultaneously
While the VA allows unlimited loan usage, managing two or more VA mortgages at the same time requires careful consideration:
- Debt-to-Income Limits: The VA requires that your total monthly debt payments (including both VA mortgages) don't exceed specific thresholds relative to your gross monthly income. Typically, lenders prefer a debt-to-income ratio of 41% or lower.
- Residual Income: Beyond debt-to-income ratios, the VA calculates residual income - the amount of money remaining after all debt payments. You'll need sufficient residual income to support both mortgages.
- Primary Residence Requirement: The VA loan program is designed for primary residences. If you're purchasing a second home while keeping the first, you'll need to certify that the new property will be your primary residence.
- Funding Fee Implications: You'll pay a VA funding fee on the second loan if your entitlement hasn't been fully restored. Planning your home sales and purchases strategically can minimize these fees.
Benefits of Using Your VA Loan Multiple Times
Long-Term Financial Advantages
By leveraging your VA loan benefit multiple times, you gain access to consistently favorable mortgage terms across your entire life. No down payment requirements mean you preserve your capital for other investments or emergencies. Lower interest rates compared to conventional loans translate to significant long-term savings, especially when spread across multiple properties over decades.
Flexibility for Life Changes
The unlimited nature of VA loans accommodates major life transitions. Military relocation, job changes, family expansion, and downsizing are all scenarios where veterans benefit from the ability to purchase new homes using their VA benefit without restriction.
No Private Mortgage Insurance (PMI)
Unlike conventional loans with less than 20% down payment, VA loans never require private mortgage insurance, saving hundreds of dollars annually regardless of how many times you use the benefit.
How VA Loans Compare to Other Programs
VA Loan vs. FHA Loans
FHA loans have less stringent down payment requirements but carry mortgage insurance premiums (UFMIP and MIP) that increase the overall cost. VA loans offer superior terms for eligible veterans with no PMI and unlimited reusability.
VA Loan vs. Conventional Loans
Conventional loans typically require 3-20% down payment and PMI if below 20%, resulting in higher borrowing costs. VA loans provide no-down-payment access and consistently lower rates across multiple purchases.
VA Loan vs. USDA Loans
USDA loans serve rural borrowers but have income limits and require adequate credit. VA loans are unrestricted by geography or income, making them more flexible for military families moving frequently.
Important Considerations Before Your Next VA Loan
Entitlement Timing: Plan your home sale and purchase timing carefully. Ensure you've fully paid off your previous VA loan and allowed time for the VA to process entitlement restoration before applying for the next loan.
Funding Fees: Understand that subsequent VA loans may incur a funding fee unless your entitlement has been fully restored. However, disabled veterans may qualify for fee exemptions.
Credit and Financial Health: Even with VA loan advantages, lenders will review your credit and income. Maintain strong financial habits between purchases to ensure smooth approval on future VA loans.
Market and Interest Rate Conditions: While you can use your VA loan unlimited times, market conditions and interest rates vary. Consider timing your purchases strategically to take advantage of favorable rate environments.
Frequently Asked Questions
Can you use a VA loan more than once?
Yes, absolutely. You can use your VA home loan benefit multiple times without any statutory lifetime limit. The key is maintaining or restoring your entitlement after each use.
What happens to your VA entitlement after you sell your home?
Once you sell the property and pay off the VA mortgage in full, your entitlement is automatically restored to its original amount. This allows you to apply for a new VA loan with full benefits on your next purchase.
Can you have two VA loans at the same time?
Yes, you can hold multiple VA loans simultaneously if you have sufficient remaining entitlement and meet the VA's debt-to-income and residual income requirements. However, this scenario is less common because managing multiple mortgages is financially demanding.
How long does it take to restore your VA entitlement?
Entitlement is restored immediately upon satisfying the original loan (paying it off completely). Once the payoff is processed and the lien is released, you can apply for a new VA loan. Verification may take a few weeks through the VA's systems.
Do you have to restore your full entitlement before getting another VA loan?
No. If you still owe on a previous VA loan, you can still use any remaining available entitlement to purchase another property. However, your borrowing capacity will be limited by the amount of entitlement already in use.
Is the VA funding fee required every time you use your loan?
The VA funding fee applies to subsequent loans unless you've fully restored your entitlement or qualify for an exemption (such as being a disabled veteran). Strategic planning around loan payoff and purchase timing can minimize funding fee costs.
Maximizing Your VA Loan Benefit Across Your Lifetime
The unlimited reusability of the VA loan is a profound advantage for veterans. By understanding entitlement restoration, managing your finances wisely, and planning your home purchases strategically, you can leverage this benefit multiple times to build wealth, adapt to life changes, and secure stable housing throughout your career and retirement.
Work with a knowledgeable VA loan specialist to understand your specific entitlement status and explore the best timeline for your next purchase. Whether you're relocating for military duty, seeking a larger home for your growing family, or investing in a better property as your career advances, your VA loan benefit is there for you - unlimited times.
Connect With Us
Please share – it really helps