VA Loan Requirements & Eligibility Criteria for 2026
 Understanding
VA loan requirements and eligibility criteria is the first step toward
achieving homeownership as a military service member. VA loans represent a
powerful home loan benefit created by the Department of Veterans Affairs to
help military families qualify for home financing without a down payment. These
VA loan requirements are designed to be favorable to veterans while protecting
lenders and ensuring borrowers can afford their monthly payments. Compared to
conventional and FHA loans, VA loans have
unique eligibility criteria that often make them more accessible to those who
served our country.
To qualify for a VA home loan, borrowers must meet specific service requirements and obtain a Certificate of Eligibility (COE). The COE proves to VA lenders that you meet the basic eligibility requirements for this home loan benefit. Veterans can obtain a certificate of eligibility through the VA's online portal, by mail, or during the application process with their VA lender.
Use our debt-to-income ratio calculator and residual income calculator to determine whether you meet the financial requirements before applying.
VA Loan Eligibility: Military Service Requirements
The VA loan eligibility requirements differ based on when and how long you served. Meeting the service requirements for a VA loan depends on your military branch and service dates. Veterans who served in the Army, Navy, Marine Corps, Air Force, or Coast Guard during specific periods qualify automatically.
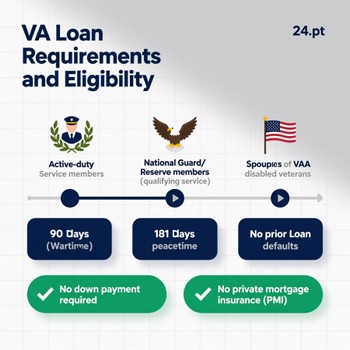
Active-duty service members typically require 90 days of consecutive service during wartime or 181 days of service during peacetime. National Guard and Reserve members must serve at least six years or complete 90 days of active duty service, including at least 30 days continuously.
The basic service requirement varies based on whether you served during wartime or peacetime periods. Additional eligibility scenarios include:
- Surviving spouses of veterans who died from service-connected conditions or while receiving VA disability compensation remain eligible for the VA loan benefit.
- Spouses of service members missing in action or prisoners of war can access VA home loan benefits.
- Service members currently on active duty can apply for a VA home loan after completing the minimum service requirement without waiting until separation.
What Military Service Documents Are Required for VA Loan Applications?
The VA loan application process requires specific documents to verify your military service record. Veterans need their DD Form 214, which provides official documentation of service dates. This form serves as the primary document for verifying loan eligibility.
Active duty service members submit a statement of service signed by their commanding officer. National Guard members provide an NGB Form 23. Surviving spouses must provide additional paperwork, including the veteran's death certificate and documentation showing the cause of death was service-connected.
VA Loan Credit Score & Financial Requirements Explained
Beyond military service, VA loan financial requirements focus on credit score, income stability, and debt-to-income ratios. Understanding these financial eligibility criteria helps you prepare before applying.
What Credit Score Is Required for a VA Loan?
VA lenders typically require a minimum credit score of 620; however, some may accept lower scores, depending on other financial factors. The VA itself doesn't set credit score requirements, leaving this decision to individual lenders. Each VA lender establishes their own credit guidelines within VA program parameters.
Your credit score affects your loan terms and interest rates. Higher scores generally result in better rates and more favorable loan conditions. Some lenders with specialty VA loan programs may work with borrowers who have credit scores as low as 580, though compensating factors would be required.
How Does Debt-to-Income Ratio Affect VA Loan Qualification?
The debt-to-income ratio (DTI) represents another important factor in loan qualification. Most VA lenders prefer a DTI below 41%, though exceptions exist. Your DTI is calculated by dividing your total monthly debt payments by your gross monthly income. Use our debt-to-income ratio calculator to estimate your DTI before applying.
- Lenders review your employment history and typically require two years of stable income.
- Self-employed borrowers need additional documentation, including tax returns and profit-and-loss statements.
- Military allowances and benefits count toward qualifying income for active duty applicants.
- Bonus income and commission-based income may be averaged over two years to establish stability.
What Is VA Loan Residual Income and Why Does It Matter?
The VA requires borrowers to meet residual income guidelines, which differ from traditional debt-to-income ratios. Residual income represents the money left over after paying all monthly debts and estimated living expenses. This requirement ensures veterans can afford their housing payments.
Regional loan centers calculate residual income based on factors such as family size, loan amount, and geographic location. The VA publishes tables showing the required residual income amounts for different situations. For example, a family of four with a $250,000 loan might need $650 in monthly residual income.
Veterans who don't meet standard residual income requirements may still qualify with compensating factors. Strong credit scores or significant cash reserves can help. Lenders evaluate the complete financial picture when making loan decisions. Use our residual income calculator to determine whether you meet this requirement.
VA Loan Types and Specialized Programs
The VA loan program offers various loan types to meet the diverse needs of homebuyers and refinancers. Understanding which VA loan type matches your goals is essential for choosing the right path to homeownership.
What Types of VA Loans Are Available?
VA purchase loans help veterans buy homes without down payment requirements for loan amounts up to the conforming loan limit in your area. Veterans buying homes above this limit may need a down payment for the portion exceeding the limit. The VA guarantees a portion of each loan, thereby reducing risk for lenders.
Streamline refinancing, known as the Interest Rate Reduction Refinancing Loan (IRRRL), helps veterans lower their current VA loan payment. This process requires minimal documentation and no new appraisal in most cases. Use our streamline refinance calculator to estimate your potential savings.
- Cash-out refinancing allows veterans to tap into their home's equity for major expenses.
- Jumbo VA loans help veterans purchase higher-priced homes in expensive markets.
- Construction loans allow veterans to build new homes with VA financing.
Specialized VA Loan Programs for Veterans with Disabilities
The VA offers adapted housing grants for veterans with specific service-connected disabilities. These grants help fund home modifications. Veterans with qualifying disabilities can receive significant financial assistance for accessibility improvements.
Native American veterans on federal trust land can access the VA Native American Direct Loan program. This specialized loan program helps tribal members purchase, construct, or improve homes on federal trust land. Veterans interested in energy-efficient homes can benefit from VA loan provisions that allow for additional debt to finance energy improvements.
Property Requirements & Home Eligibility for VA Loans
Beyond borrower eligibility, the property itself must meet VA standards. Understanding property requirements ensures your dream home qualifies for VA financing.
What Property Standards Must a Home Meet for VA Loan Financing?
VA loan properties must meet specific safety, structural, and livability standards. The VA requires a professional appraisal to verify that homes meet these requirements. Properties must be move-in ready and serve as the veteran's primary residence.
The VA property requirements focus on health and safety rather than cosmetic condition. Homes need proper heating, plumbing, electrical systems, and structural integrity. The appraiser identifies any required repairs that must be completed before the loan closing. Veterans cannot use VA loans for investment properties or vacation homes. The loan benefit is explicitly designed for primary residences.
- Properties must have safe drinking water and adequate sewage disposal systems.
- The VA may require specific repairs identified during the appraisal process.
- Home inspections are recommended though not required by the VA.
- Lead-based paint disclosures are required for homes built before 1978.
- Flood insurance is required if the property is in a flood zone.
Can I Finance a Manufactured or Modular Home with a VA Loan?
The VA allows financing for manufactured homes that meet specific requirements. The home must be classified as real estate rather than personal property. Veterans must own or lease the land on which the manufactured home is situated.
Modular homes generally qualify for VA loans if they meet local building codes and VA property standards. These factory-built homes must be permanently attached to foundations. Condominiums require VA approval of the entire project before individual units can receive VA loan financing. The condo project must meet the VA's occupancy, financial, and legal requirements.
Getting Started: Your VA Loan Application Process
Ready to apply for a VA loan? Understanding the application timeline and preparation steps will help you move through the process smoothly.
How Do I Obtain My Certificate of Eligibility for a VA Loan?
The first step in applying for a VA home loan involves obtaining your Certificate of Eligibility. Veterans can request their COE online through the VA website at VA.gov. The online process requires basic personal information and service details. Processing typically takes a few business days.
Veterans who cannot obtain their COE online can submit VA Form 26-1880 by mail to their regional loan center. Some VA lenders can also request COEs on behalf of their clients during the application process. Getting your COE early in the process demonstrates seriousness to sellers and real estate agents.
How Do I Choose a VA Lender and Begin the Application?
Shopping for the right VA lender requires research and comparison of different options. Veterans should compare interest rates, fees, and customer service reviews. Many lenders specialize in VA loans and are well-versed in the program's unique aspects.
- Pre-approval helps veterans understand their buying power before house hunting.
- Interest rates can vary significantly between different VA lenders - shopping around can save thousands.
- Ask lenders about their VA loan experience and customer satisfaction ratings.
How Long Does the VA Loan Process Take from Application to Closing?
The loan application process typically takes 30-45 days from application to closing. Veterans should gather the required documents well in advance. Working with experienced VA loan specialists can help streamline the process. Veterans who face challenges during the application process can contact the VA for assistance.
Frequently Asked Questions About VA Loan Requirements
What are the military service requirements for a VA loan?
VA loan service requirements depend on your military branch and when you served. Active-duty service members typically require 90 days of consecutive service during wartime or 181 days of service during peacetime. National Guard and Reserve members must serve at least six years or complete 90 days of active duty service, including at least 30 days continuously. Veterans who served in the Army, Navy, Marine Corps, Air Force, or Coast Guard during specific periods qualify automatically. Surviving spouses of veterans who died from service-connected conditions also remain eligible for the VA loan benefit.
What credit score do I need for a VA loan?
VA lenders typically require a minimum credit score of 620; however, some may accept lower scores depending on other financial factors. The VA itself doesn't set credit score requirements, leaving this decision to individual lenders. Each VA lender establishes their own credit guidelines within VA program parameters. Your credit score affects your loan terms and interest rates. Higher scores generally result in better rates and more favorable loan conditions. Some specialty lenders may accept scores as low as 580 with compensating factors.
What documents do I need to verify military service for a VA loan?
The VA loan application process requires specific documents to verify your military service record. Veterans need their DD Form 214, which provides official documentation of service dates and serves as the primary document for verifying loan eligibility. Active duty service members submit a statement of service signed by their commanding officer. National Guard members provide an NGB Form 23. Surviving spouses must provide additional paperwork, including the veteran's death certificate and documentation showing the cause of death was service-connected.
What is residual income and why does it matter for VA loans?
Residual income represents the money left over after paying all monthly debts and estimated living expenses. The VA requires borrowers to meet residual income guidelines, which differ from traditional debt-to-income ratios. This requirement ensures veterans can afford their housing payments. Regional loan centers calculate residual income based on factors such as family size, loan amount, and geographic location. The VA publishes tables showing the required residual income amounts for different situations. Veterans who don't meet standard residual income requirements may still qualify with compensating factors such as strong credit scores or significant cash reserves.
Can I get a VA loan with a low credit score or past bankruptcy?
While VA lenders typically prefer a minimum credit score of 620, some lenders may accept scores lower than 580 depending on other financial factors and compensating factors. Strong credit history, significant cash reserves, or strong residual income can help offset a lower score. Lenders evaluate the complete financial picture when making loan decisions. Veterans with past bankruptcy may still qualify, though lenders will review the circumstances and may require additional documentation or compensating factors to approve the loan.
What is a Certificate of Eligibility (COE) and how do I get one?
A Certificate of Eligibility (COE) proves to VA lenders that you meet the basic eligibility requirements for the VA home loan benefit. The COE verifies your military service record and confirms your eligibility. Veterans can obtain a COE through the VA's online portal at VA.gov, by mail using VA Form 26-1880, or during the application process with their VA lender. The online process requires basic personal information and service details. Some VA lenders can also request COEs on behalf of their clients during the application process.
Connect With Us
Please share – it really helps